Blogerroom
Gold Is 26% Below Its Peak While Central Banks Keep Buying
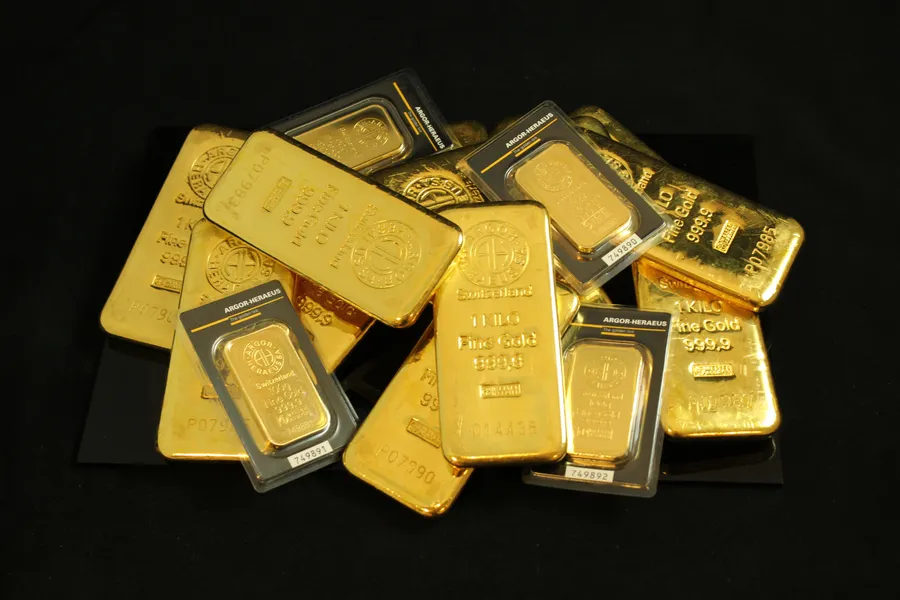
Gold has fallen to about $4,110, 26% under January's record, as 5.3% Treasury yields bite, yet central banks bought 289 tonnes in Q2, a second-quarter record.
Gold reached a record of roughly $5,595 an ounce in January. On Thursday it slipped to about $4,110 in early Asian trading, a near two-month low, according to FXStreet, which puts it around 26% below the peak. That is an odd picture for a year in which oil has topped $100, inflation has climbed in Europe and Australia, and central banks have been raising rates to fight it.
The usual story says gold rises when inflation rises. This year it did not.
What Pushed Gold Down
The pressure comes from the bond market. Gold pays no interest, so when safe government bonds offer more, holding it costs more. The 10-year US Treasury yield closed at 5.31% on Oct. 5, and the 30-year joined it at a 24-year high, according to a market analysis from Discovery Alert. Blogerroom has followed that climb since a weak Treasury auction sent yields to near 20-year highs.
The dollar adds to it. A firmer dollar makes gold more expensive for buyers in other currencies. The Dollar Index was around 102 this week, FXStreet reported.
The Federal Reserve is the trigger. Investing.com noted on Sept. 28, when gold dropped nearly 4% in a session, that the Fed had hiked rates for the first time in more than three years and signaled more tightening to come. Blogerroom covered that decision as the Fed's unanimous 12-0 hike. Since then, markets have priced about a 77% chance of the Fed holding in October, FXStreet reported, but December hike odds remain elevated.
The Inflation-Hedge Puzzle
Why did a supposed inflation hedge fall as inflation rose? Because the market cares less about inflation itself than about what central banks do about it. If higher prices lead to higher rates, then real yields, which are yields minus inflation, go up, and that hurts gold. Tata Mutual Fund argued in its October outlook that the fall is driven by macroeconomic factors, mainly Treasury yields and the dollar, and not by a deterioration in structural demand, according to Business Standard.
My view: this year is a reminder that gold is a bet on real interest rates and currency confidence as much as an inflation shield. In an oil-driven price shock, where central banks respond by tightening, the first effect on gold is negative.
Who Is Still Buying
Official buyers have not left. The World Gold Council reported that central banks and other official institutions bought a net 289 tonnes in the second quarter of 2026, up 62% from 177.9 tonnes a year earlier and the highest for any second quarter on record. Forty-five percent of central banks surveyed said they planned to increase gold reserves over the next 12 months. By mid-year, Poland had added 82 tonnes, Uzbekistan 41 and China 40, according to data compiled by the council.
Chinese imports have also surged. The Tata Mutual Fund report said they exceeded 1,000 tonnes in 2026, already above the full-year 2025 total, driven by retail purchases, ETF inflows and central-bank buying.
Two Kinds of Demand
The market has split in two. Gold-backed exchange-traded funds, the vehicle for Western investors, recorded 45 tonnes of outflows in the second quarter, and the Tata report said outflows increased after March amid the US-Iran conflict before stabilizing from July. Central banks moved the other way.
That matters for the price floor. Reuters reported that gold has stayed above $4,000 despite elevated bond yields, supported by central-bank buying, geopolitical concerns and reserve diversification. Discovery Alert pointed out that spot gold slipped only 0.3% on Oct. 6 even as yields hit a 24-year high, which suggests a bid underneath. Reuters framed the retreat from January as largely profit-taking, not a collapse in demand, that analysis said.
Reserve managers care about holding assets that are not another government's debt, not about what yields are doing this week, so their buying is far less sensitive to the Fed. Western ETF investors respond to rates immediately. Gold's price is now a tug of war between the two.
What to Watch Next
First, yields. If the 10-year keeps rising from 5.3%, expect gold to test lower levels, with analysts at FXStreet watching $4,100 as the first support. Second, oil and inflation data, because stronger prices raise the odds of more Fed hikes. Third, whether ETF outflows stay stalled or reverse, since that would show whether Western investors are returning.
Oil is the link between the two stories. As Blogerroom reported when OPEC+ held its quotas steady, the supply shock has kept crude above $100 and fed the inflation that central banks are fighting. Tata Mutual Fund suggests investors spread any purchases over several months rather than trying to time a bottom, which is its institutional view, not a recommendation from Blogerroom.
Gold can fall further or rebound. This article is general information, not investment advice.
Written by
Mr. Jitendra Bhatt
Deep understading of finance area and writer covering markets, investing, and economic policy.